What is the overarching scope of the Low-Flow Plumbing Fixtures Market?
Our analysis indicates that the Low-Flow Plumbing Fixtures Market encompasses water-conserving sanitaryware designed to drastically reduce domestic and commercial water consumption without sacrificing operational performance. Industry significance centers on municipal compliance with environmental statutes enforced by bodies like the EPA WaterSense program. Key raw materials include brass, vitreous china, and engineering-grade polymers processed through precision casting and injection molding.
Structural Growth Drivers and Market Restraints
The data suggests that strict municipal building codes and severe drought conditions act as primary growth catalysts. Conversely, market restraints involve the high initial capital expenditure required for commercial retrofits and consumer perception regarding reduced pressure in fixtures like fixed showerheads. Supply chain bottlenecks involving virgin brass alloy procurement represent a persistent logistical hurdle for manufacturers.
Emerging Trends and Technological Shifts
The shift toward touchless actuation and smart water metering is reshaping the Low-Flow Plumbing Fixtures Market industry trends. Innovations by market participants focus on integrating IoT sensors into dual-flush toilets and electronic faucets to track real-time consumption metrics, appealing directly to green-building certification standards like LEED.
COVID-19 Impact and Post-Pandemic Recovery
Pandemic-induced supply chain disruptions and commercial real estate freezes severely impacted distribution channels. However, our research reveals an accelerated post-pandemic recovery driven by residential renovation booms. Consumers invested heavily in home upgrades, boosting demand for premium handheld showerheads and touchless kitchen faucets.
Competitive Benchmarking and Market Concentration
The competitive landscape features intense rivalry among multinational sanitaryware giants. Established entities like Kohler Company, Toto Ltd., and Moen Incorporated dominate through extensive distribution networks. Strategic positioning relies heavily on proprietary aerator technology and aesthetic differentiation across both residential and industrial product tiers.
Executive Summary of the Low-Flow Plumbing Fixtures Market
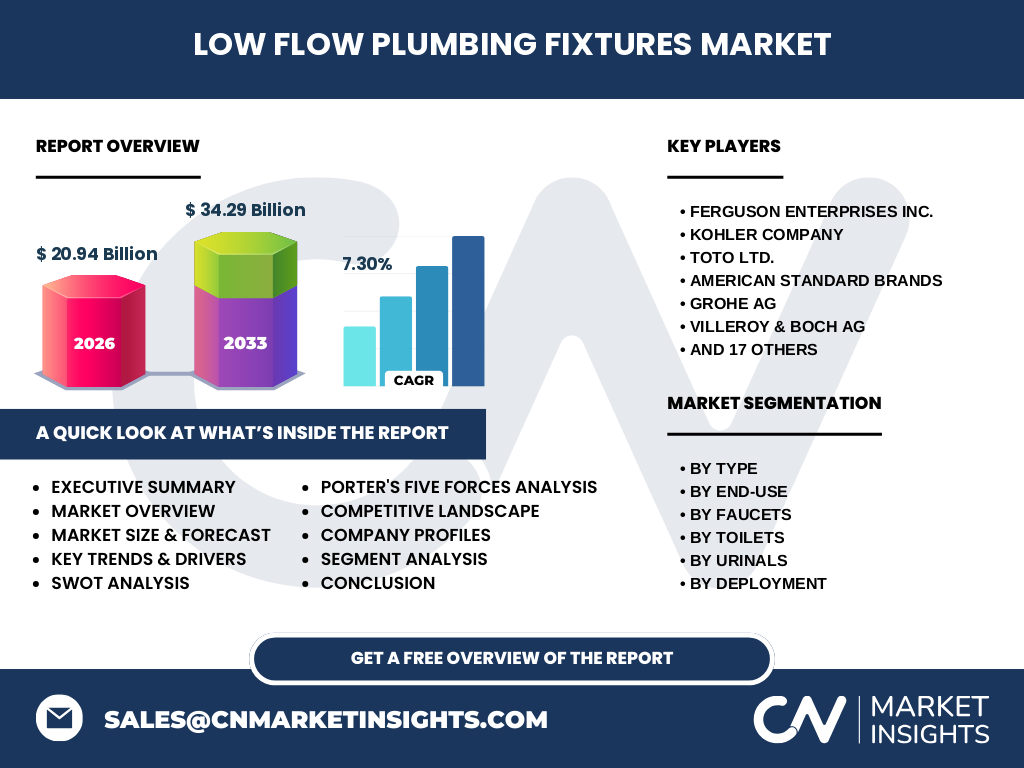
Our proprietary research demonstrates that the Low-Flow Plumbing Fixtures Market size stands at 20.94 Billion in 2026. Driven by escalating sustainability mandates, the sector is poised for robust expansion, reflecting strong commercial viability and long-term investor appeal across global regions.
Long-Term Market Forecast Through 2033
Based on our econometric modeling, the market is projected to reach 34.29 Billion by 2033, expanding at a steady CAGR of 7.30% from 2027. This trajectory underscores sustained demand fueled by urban densification and mandatory green building regulations globally.
Comprehensive Segmentation Analysis
Market segmentation covers type, end-use, faucet variants, toilet mechanisms, urinal styles, deployment methods, and distribution channels. Key categories include faucets, showerheads, toilets, urinals, and specialized items like bidets and faucet aerators. Deployment is split between new construction and repair and remodeling, while distribution spans online sales and offline sales.
Geographic Distribution and Regional Performance
Regional performance varies based on local water scarcity indexes and strictness of plumbing codes. North America and Europe lead adoption due to stringent environmental regulations, whereas Asia-Pacific represents the fastest-growing frontier driven by rapid urbanization and massive infrastructure investments in emerging economies.
In-Depth Regional Review and Market Constraints
North American growth is anchored by EPA WaterSense specifications and California's rigorous efficiency standards. Meanwhile, localized market constraints in developing Asian sectors involve fragmented distribution networks and consumer price sensitivity, though government-backed smart city initiatives are rapidly offsetting these hurdles.
Strategic Positioning of Leading Companies
Industry participants deploy distinct competitive strategies to capture market share. Companies like Delta Faucet Company and American Standard Brands focus on innovative water-saving cartridges, while specialized players such as Sloan Valve Company and Zurn Industries LLC dominate the commercial and industrial institutional segments with heavy-duty flush valves.
Porter's Five Forces Analysis of Competitive Intensity
Bargaining power of buyers remains moderate to high due to the abundance of commoditized sanitaryware. Threat of substitutes is low given regulatory mandates. Competitive rivalry is fierce, pushing incumbent brands like Grohe AG and Hansgrohe SE to continuously innovate in design and water-saving performance.
SWOT Analysis of the Industry Ecosystem
Strengths include robust regulatory tailwinds and proven water-saving technologies. Weaknesses stem from complex installation requirements for advanced commercial systems. Opportunities lie in IoT-enabled smart fixtures, while major threats involve raw material price volatility, particularly for copper and high-grade polymers.
Value Chain and Supply Chain Dynamics
The value chain flows from raw material extraction of brass, ceramics, and polymers to precision manufacturing, assembly, and distribution via wholesale plumbing supply houses, retail home centers, and online sales channels. Value capture is heavily concentrated among brand owners controlling proprietary aerodynamic and flow-regulation patents.
Investment Insights and High-Potential Opportunities
Our analysis highlights high-potential investment areas in retrofit-friendly products such as faucet aerators and waterless urinals. Investors should prioritize manufacturers with vertically integrated supply chains capable of navigating raw material price fluctuations while meeting strict international certification standards.
Conclusion and Strategic Takeaways
The Low-Flow Plumbing Fixtures Market analysis confirms that regulatory compliance and consumer eco-consciousness are permanent structural shifts. Stakeholders must embrace technological integration and digital marketing channels to maintain competitive advantage through the forecast period ending in 2033.
Rigorous Research Methodology and Data Triangulation
Baseline estimates are triangulated using a multi-tiered approach combining primary stakeholder interviews with C-suite executives, exhaustive trade registry data from major global ports, and secondary macroeconomic indicators from international water councils and building federation reports.
Scope of the Report and Coverage Parameters
This report covers global market sizing, segmental evaluations, and competitive intelligence for the Low-Flow Plumbing Fixtures Market from 2026 through 2033. Limitations include exclusion of informal gray-market plumbing imports and custom artisan installations not captured by standardized trade statistics.
Recent Corporate Developments and Strategic Moves
Recent industry activity highlights aggressive M&A strategies and eco-friendly product rollouts. Major players like Ferguson Enterprises Inc., Kohler Company, and Toto Ltd. have formed strategic partnerships with prop-tech platforms to streamline commercial distribution, alongside launching advanced smart-sensor fixtures to capture rising demand.